

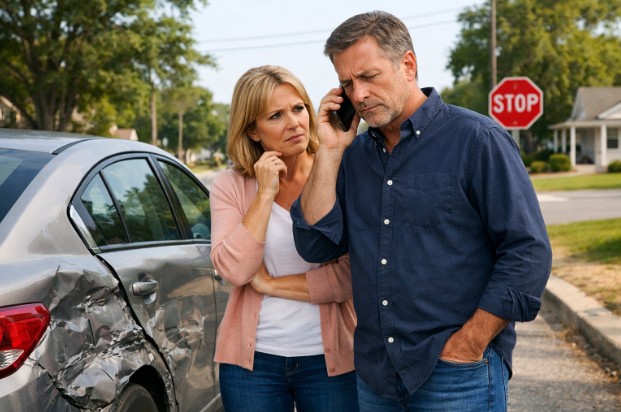
A driver can carry liability insurance and still lack enough coverage to pay for a serious accident. Underinsured motorist laws address that gap through UIM coverage, but the amount available and the method for calculating benefits differ among states and insurance policies. The NAIC describes UIM coverage as protection when an at-fault driver’s insurance is insufficient for the loss.
When a Driver Becomes Underinsured
An underinsured driver is not the same as an uninsured driver. The at-fault motorist has liability insurance, but available limits may be inadequate compared with covered damages.
Someone reviewing independent web reading after an accident should distinguish general information from the actual UIM definition in the policy. State law or policy wording may determine when the underinsured threshold has been reached.
How Coverage Limits Affect Recovery
UIM claims commonly involve several numbers: the at-fault driver’s liability limit, the claimant’s UIM limit, proven damages, and potentially other applicable insurance. How those amounts interact is jurisdiction-specific.
Comparing general digital resources cannot establish the amount legally recoverable under an individual contract. Policyholders should review declarations, endorsements, and provisions addressing limits, multiple vehicles, other insurance, and payments received from responsible parties.
| Coverage Question | Key Factor | Why It Matters |
|---|---|---|
| Is UIM triggered? | Other driver’s limits | Rules vary by jurisdiction |
| How much is available? | Your UIM limits | Sets contractual boundaries |
| Are damages proven? | Records and evidence | Supports claim valuation |
| Is other insurance involved? | Policy coordination | May affect calculation |
The Claim and Settlement Process
After determining that another driver may be underinsured, the claimant normally needs evidence establishing fault and damages. Medical documentation, income records, expert reports when appropriate, and information about the responsible driver’s insurance may become important.
Research through online news material can provide general context, but settlement decisions should be based on the policy and applicable law. Some policies or jurisdictions may also impose procedural requirements before a claimant resolves the underlying liability claim.
Mistakes That Can Reduce a UIM Claim
A major mistake is assuming UIM simply pays the difference between total damages and the other driver’s insurance in every state. Different legal frameworks can produce different calculations.
Claimants can also create problems by settling quickly without checking whether their own policy imposes notice, consent, preservation, or cooperation requirements. Another misconception is that buying high UIM limits guarantees payment up to those limits. Damages still need to be supported, and coverage defenses can remain relevant.
When Legal Review May Be Appropriate
State-specific legal advice can be useful when damages exceed the responsible driver’s limits, multiple insurers are involved, an insurer raises a coverage defense, or a settlement could affect UIM rights. Legal review may also matter when deadlines, arbitration provisions, consent requirements, or disputed medical causation become significant. These issues depend heavily on the governing jurisdiction and policy wording.
Frequently Asked Questions
When can I make an underinsured motorist claim?
Generally, a potential UIM claim arises when an insured suffers covered damages caused by an at-fault motorist whose applicable liability coverage is insufficient under the governing policy and state rules.
Can I collect both liability insurance and UIM benefits?
Potentially. Liability insurance from the at-fault driver and UIM coverage may both be relevant, but the way payments are coordinated varies. Policy terms and state law determine the available recovery structure.
Is underinsured motorist coverage automatically included?
Not everywhere. UIM requirements vary among states, and policies can differ. The NAIC notes that some states require uninsured or underinsured motorist protection while coverage structures are not uniform nationwide.
Review the Policy Before Settling
UIM disputes often turn on details that appear minor until a settlement is signed. Confirm the other driver’s limits, document your losses, read your own endorsements, and determine whether state law creates additional procedural requirements before giving up rights against any party.
This article provides general legal information and is not a substitute for advice from a qualified attorney regarding a specific claim.

Leave a Reply